Federal employee health insurance after retirement is one of the most valuable benefits you can carry into your post-government life — yet many feds misunderstand how it actually works. The Federal Employees Health Benefits (FEHB) program covers more than 8 million current and retired federal workers, dependents, and survivors, according to the U.S. Office of Personnel Management's official program data.
The problem is that the rules around eligibility, the 5-year requirement, and how FEHB coordinates with Medicare trip up even seasoned employees. This article breaks down the five most important things you need to know before you retire, including how to keep your coverage, avoid costly mistakes, and make FEHB work alongside Medicare.
1. The 5-Year Rule: Your Ticket to Keeping FEHB Coverage
The single most important requirement for keeping federal employee health insurance after retirement is the "5-year rule." You must have been enrolled in FEHB for the five consecutive years immediately before your retirement date. Miss this window and you lose coverage permanently — there is no appeal process.
OPM's official retirement guidance states that "you must have been continuously enrolled (or covered as a family member) in any FEHB Program plan for the five years of service immediately before retirement." This means coverage under a spouse's FEHB plan counts toward your five years, which many employees don't realize.
The five-year clock starts on the effective date of your enrollment, not when you first became eligible. If you waived coverage for years and only enrolled 4 years and 11 months before retiring, you're out of luck. Understanding federal employee health insurance after retirement requirements early gives you time to correct course if needed.
How to apply this: Log into your OPM Retirement Services account today and verify your FEHB enrollment start date. If you're within 12 months of retirement and haven't met five years, you cannot fix it retroactively.
2. Your Premium Costs Stay the Same — But Your Tax Treatment Changes
Many federal employees assume their health insurance premiums drop after retirement. They don't. You pay the same premium as active employees — the government continues paying its share (typically 72-75% of the total premium, based on OPM's annual premium allocation charts).
The key difference is tax treatment. While working, your FEHB premiums are deducted pre-tax through the premium conversion plan. After retirement, premiums come out of your annuity after taxes. This effectively increases your out-of-pocket cost by your marginal tax rate.
There's one exception: retired public safety officers can exclude up to $3,000 annually from taxable income for health insurance premiums under IRS rules. The IRS explains this exclusion applies to "retired public safety officers" including law enforcement, firefighters, and certain rescue personnel. For everyone else, planning for federal employee health insurance after retirement means budgeting for the post-tax premium shift.
How to apply this: Budget for post-tax premium payments by calculating your expected annuity after taxes, then subtracting your current FEHB premium. Use the OPM Retirement Calculator to model your net annuity.
3. FEHB and Medicare: The Coordination Strategy That Saves Thousands
Once you turn 65, Medicare becomes your primary coverage and FEHB shifts to secondary. How you handle this transition can save or cost you significant money over a 20-30 year retirement. This is where federal employee health insurance after retirement planning becomes especially critical.
Most federal retirees keep both Medicare Part A (free) and Part B (premium-based) alongside FEHB. With both, FEHB typically waives deductibles, copays, and coinsurance that Medicare doesn't cover. Without Part B, FEHB may pay as primary — but you'll owe the Part B late enrollment penalty (10% per 12-month delay, permanently) if you enroll later.
Some retirees choose to suspend FEHB and rely solely on Medicare Advantage plans. This is risky: if you suspend FEHB, you can re-enroll during Open Season, but you lose the guaranteed issue protections FEHB provides. Many retirees find that keeping federal employee health insurance after retirement alongside Medicare offers the most comprehensive safety net.
How to apply this: Three to six months before turning 65, contact your FEHB plan's customer service and ask for their "Medicare coordination of benefits" document. Compare keeping Part B versus dropping it using actual premium numbers from Medicare.gov.
4. Survivor Benefits: What Happens to FEHB When You Die
Federal employee health insurance after retirement extends to your surviving spouse — but only if you elect a survivor annuity. This is a critical decision point at retirement.
If you choose a full or partial survivor annuity for your spouse, they keep FEHB coverage for life, paying the same premiums. If you elect no survivor benefit, your spouse loses FEHB on the day you die. There is no option to purchase FEHB later.
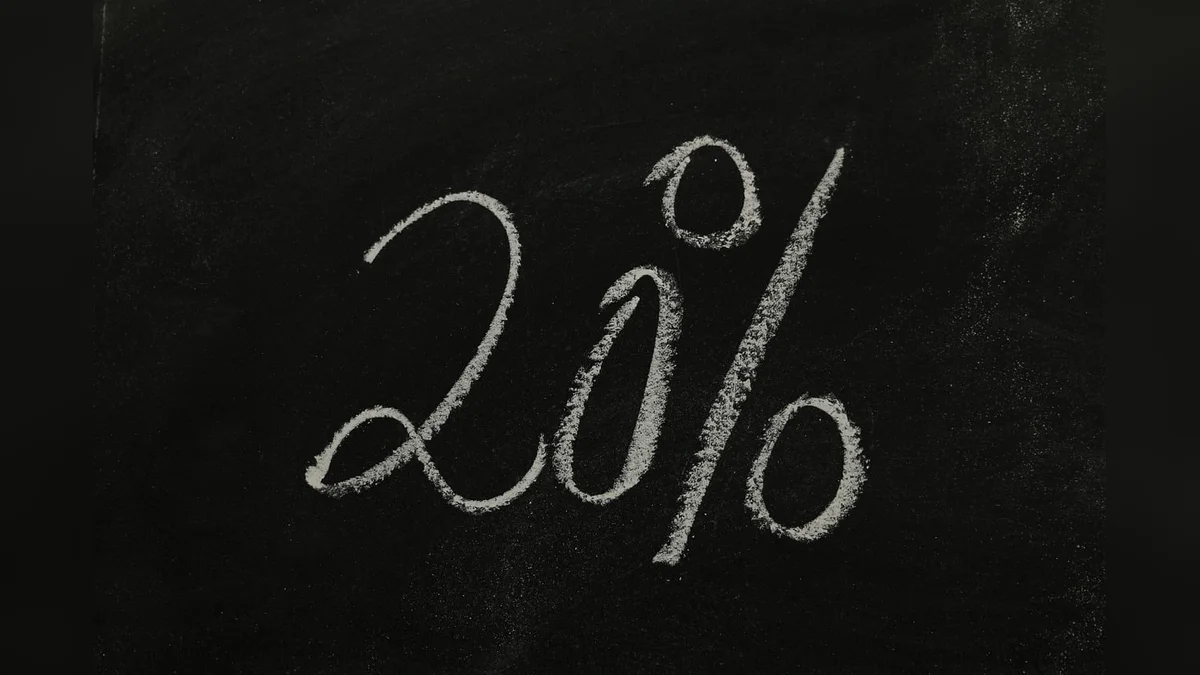
The cost of a survivor annuity is a permanent reduction in your own annuity — typically 10% for a full survivor benefit (50% of your annuity) or 5% for a partial benefit (25%). This election is generally irrevocable after retirement.
A common scenario: a retiring employee with a younger spouse declines survivor benefits to maximize their own annuity, not realizing the spouse will lose health coverage entirely. The spouse then faces the individual market, often at much higher cost for lesser coverage.
Protecting your spouse's access to federal employee health insurance after retirement should factor heavily into your survivor annuity decision.
How to apply this: Before retiring, request a personalized annuity estimate showing all three survivor options from your agency's benefits office. Compare the lifetime cost of the survivor reduction against the cost of individual market coverage for your spouse.
5. Changing Plans After Retirement: More Flexibility Than You Think
Contrary to popular belief, you're not locked into your current FEHB plan forever. Retirees can change plans during the annual Federal Benefits Open Season, which typically runs from mid-November to mid-December. Staying flexible with federal employee health insurance after retirement can save you thousands over the years.
You can also make changes outside Open Season for qualifying life events: marriage, divorce, birth or adoption of a child, or a move out of your plan's service area. This flexibility matters because plan networks and premiums change annually.
OPM publishes plan comparison tools each year, and many retirees find that switching from a high-option plan to a standard or consumer-driven plan saves hundreds monthly. The trade-off is higher deductibles and out-of-pocket maximums. Reviewing your federal employee health insurance after retirement options annually is a habit worth building.
How to apply this: Each fall, review the OPM plan comparison chart for your ZIP code. Compare at least three plans using your actual prescription list and expected medical usage, not just the premium.
Comparing FEHB Options After Retirement
| Factor | What to check | Action to take |
|---|---|---|
| 5-year rule compliance | FEHB enrollment start date | Verify via OPM account 12+ months before retiring |
| Premium tax treatment | Pre-tax vs. post-tax deduction | Recalculate net annuity with post-tax premiums |
| Medicare coordination | Part B enrollment status | Contact FEHB plan 6 months before age 65 |
| Survivor coverage | Survivor annuity election | Request all three annuity estimates |
| Annual plan changes | Open Season dates | Compare 3+ plans each November |
Frequently Asked Questions About federal employee health insurance after retirement
What happens if I retire before meeting the 5-year FEHB requirement?
You lose FEHB coverage permanently, with no appeal or reinstatement option. One exception exists: if you retire due to disability, OPM may waive the five-year requirement in certain circumstances.
A scenario where this matters: an employee who enrolled in FEHB at age 58 and retires at 62 has only four years — they'd need to work one more year or lose federal employee health insurance after retirement eligibility entirely.
This is why tracking your enrollment start date for federal employee health insurance after retirement purposes is essential from day one.
Can I suspend FEHB and re-enroll later?
Yes, you can suspend FEHB coverage and re-enroll during any future Open Season. This is common for retirees who move overseas or enroll in a spouse's employer plan. However, suspension means you're uninsured under FEHB during that period, and if you die while suspended, your survivor loses FEHB rights. Re-enrollment requires a qualifying event or waiting for Open Season.
Weigh carefully whether temporarily dropping federal employee health insurance after retirement is worth the risk.
Does FEHB cover dental and vision after retirement?
Standard FEHB plans include limited dental and vision coverage, but most retirees supplement with the Federal Employees Dental and Vision Insurance Program (FEDVIP). FEDVIP is separate from FEHB and requires its own enrollment. You can enroll in FEDVIP after retirement even if you weren't enrolled while working, unlike FEHB which requires the five-year rule.
Knowing what federal employee health insurance after retirement includes — and what it doesn't — helps you plan supplemental coverage.
How does FEHB work if I move to another state after retiring?
Most FEHB plans are national, but some regional HMOs limit coverage to specific service areas. If you move out of your plan's network area, you qualify for a special enrollment period to switch plans. Check whether your current plan covers your destination state — retirees who move to Florida or Arizona often switch from regional HMOs to national PPO plans.
Your federal employee health insurance after retirement should travel with you, but plan networks vary.
Can I keep FEHB if I return to federal service after retiring?
Yes, but your prior retirement ends and you become an active employee again. Your FEHB enrollment continues without interruption, and the five-year rule resets based on your new retirement date. This matters for retirees who return part-time: you must work long enough in the new appointment to meet the five-year requirement again for federal employee health insurance after retirement.
The continuity of federal employee health insurance after retirement through a return to service requires careful planning.
Key Takeaways
- The 5-year continuous FEHB enrollment rule is non-negotiable — verify your date now
- Premiums stay the same after retirement but shift from pre-tax to post-tax
- Coordinating FEHB with Medicare Part B saves most retirees significant money over time
- Your spouse's FEHB coverage depends entirely on your survivor annuity election
- You can change FEHB plans every Open Season — don't stay in an expensive plan out of inertia
Your next step is simple: pull up your latest Leave and Earnings Statement, find your FEHB enrollment code, and confirm your enrollment start date with your HR office. If you're within two years of retirement, schedule a pre-retirement counseling session through your agency's benefits center.
The decisions you make now about federal employee health insurance after retirement will affect your financial security for decades. Taking action today ensures your federal employee health insurance after retirement remains secure when you need it most.





